

We review your visa, income and deposit with a free assessment, then show you how much you could borrow and which lenders accept your visa type.

We gather your documents, apply with the lender best suited to your visa, secure your preapproval and help you line up FIRB approval where it’s needed.

Once you’ve found an eligible new build, off the plan property or block of land, we finalise your loan and guide you through to settlement.
Yes. Many Australian lenders approve home loans for temporary visa holders, although the rules are stricter than for citizens and permanent residents. Your visa type, the time left on your visa, your income, your deposit and whether you’re buying with an Australian partner all shape how much you can borrow and which lenders will consider you.
We’re accredited with a wide panel of banks and lenders, so we can match your visa and income to the lenders whose policies suit you, then negotiate your rate, fees and loan structure.
Not every property in every location is eligible for all loan schemes. We will guide you while considering all the factors at play so you can choose the right property for your visa type and needs.
Consider Gold Coast and Cairns as it is a great option with a relatively affordable property market. We’re local experts, accredited with all major banking institutions and lenders, plus we’re affiliated with insurers via the Steadfast group. This means we can get a good deal on your loan insurance as a temporary visa holder.
Lenders commonly consider applicants on these temporary visas.
Lenders generally prefer at least 12 months remaining on your visa, and some want longer. If you hold a permanent visa such as 189, 190, 186, 801 or 132, you’re treated the same as a permanent resident, so FIRB approval doesn’t apply and your lender options are much wider. Read more in our 491 visa home loan guide.
Most temporary visa holders buying on their own need approval from the Foreign Investment Review Board (FIRB) before buying residential property, and an application fee applies. It’s important to get the timing right so your approval and your finance are both in place before your contract becomes unconditional. We help coordinate your FIRB application alongside your loan.


We help temporary visa holders get their home loans approved anywhere in Australia, with local teams on the Gold Coast and in Cairns.
Every lender has its own policy, but most will look closely at
We’ll tell you upfront where your application is strong and what, if anything, to work on before applying.
Buying on a temporary visa involves a few extra steps, and getting the order right protects your deposit. Before you sign, make sure you
For off the plan purchases, also allow for the time between signing and settlement. Your lender will reassess your income and visa closer to completion, so any change in your job or visa status during the build can affect your loan.
Not sure where you stand? We’ll walk you through each step and work with your conveyancer so nothing is missed.
Using a mortgage broker can sometimes be a hit and miss process. Luckily for me, I came across Lauren Eakins on a google search and all the reviews are accurate.Lauren guided me through the mortgage process with enthusiasm and eagerness, finding great deals that suited my circumstances.
Highly recommend Lauren and her team. They are extremely professional, knowledgeable, and genuinely cares about getting the best outcome for their clients. They will go above and beyond to help you structure your loan correctly and will always be available to answer questions. If you’re looking for reliable advice and excellent service, this is the team to trust.
Lauren and the team have once again helped us secure the best available loan and rate for our mortgage. Seamlessly settled just before Christmas almost 3 years to the day since our first home settled. We wouldn’t trust anyone else! Five stars all the way! We have already referred multiple people and will continue to do so. Merry Christmas to the Eakins Finance and Insurance team.
Yes. Many lenders will approve home loans for temporary visa holders who have stable income in Australia, a suitable deposit and enough time left on their visa. Lending rules are stricter than for citizens and permanent residents, so choosing a lender whose policy suits your visa is the key to approval.
The Foreign Investment Review Board (FIRB) reviews foreign investment in Australia, including residential property purchases by temporary residents. Most temporary visa holders buying on their own need FIRB approval before they buy, and an application fee applies. You don't need approval if you're buying with your Australian citizen or permanent resident spouse as joint tenants.
Australian citizens, permanent residents and New Zealand citizens don't need FIRB approval. Temporary residents buying with their Australian citizen, permanent resident or New Zealand citizen spouse as joint tenants are also exempt. Buying as tenants in common with a spouse doesn't qualify for this exemption.
Generally no. From 1 April 2025 until 30 June 2029, foreign persons including temporary residents are banned from buying established dwellings unless a limited exception applies. The main exception for most visa holders is buying with an Australian citizen or permanent resident spouse as joint tenants.
With FIRB approval you can buy a new home, an off the plan property or vacant land to build on. If you're buying with an eligible Australian spouse as joint tenants, you can also buy an established home.
Yes. The 482 Skills in Demand visa (formerly the TSS visa) is one of the visas lenders are most comfortable with, particularly when you have steady employment with your sponsor and at least 12 months left on your visa. Your deposit and borrowing limit will depend on your income and whether you're buying with an Australian partner.
Yes. Partner visa holders (820 and 309) often have strong options, especially when buying with their Australian citizen or permanent resident partner. In that situation, some lenders apply standard lending policy and will lend up to 95% of the property value.
It's possible, though harder. Lenders look at the visa you held before and the one you've applied for, and approval is assessed case by case. Buying with an Australian citizen or permanent resident partner makes approval much more likely. Expect lenders to ask for extra documentation.
Buying with an Australian citizen or permanent resident partner, you may need as little as 5% plus costs. Buying on your own, many lenders require at least 20%, and you'll also need to cover FIRB fees, foreign buyer stamp duty and legal costs.
Your borrowing power depends on your income, employment history, living expenses, existing debts, deposit and the lender's policy for your visa. Many temporary visa holders buying alone can borrow up to 80% of the property value, and higher amounts are possible in some situations. A free assessment will give you a clear figure.
Temporary residents buying in Queensland generally pay Additional Foreign Acquirer Duty of 8% on top of standard transfer duty. There's also a 3% land tax surcharge if the property is liable for land tax, the FIRB application fee, and a possible annual vacancy fee if the home sits empty for more than half the year.
In most cases no. Queensland's First Home Owner Grant requires at least one buyer to be an Australian citizen or permanent resident, and the federal Home Guarantee Scheme has the same requirement. If you're buying with an eligible partner, you may be able to access these programs together.
Some lenders will accept foreign income, although they usually count only part of it and may charge a higher rate. Income earned in Australia is assessed much more favourably. We can tell you which lenders will consider your overseas income and how it affects your borrowing power.
Yes, with FIRB approval you can buy a new dwelling or vacant land and rent it out. Established homes aren't available to temporary residents during the current ban. Investment loans for visa holders often need a larger deposit, so it's worth getting advice early.
Your loan continues as normal as long as you keep making repayments. If you become a permanent resident, you may be able to refinance to a better rate or product, because you'll qualify for standard lending policy. Talk to us when your PR is granted and we'll review your options with our refinancing service.
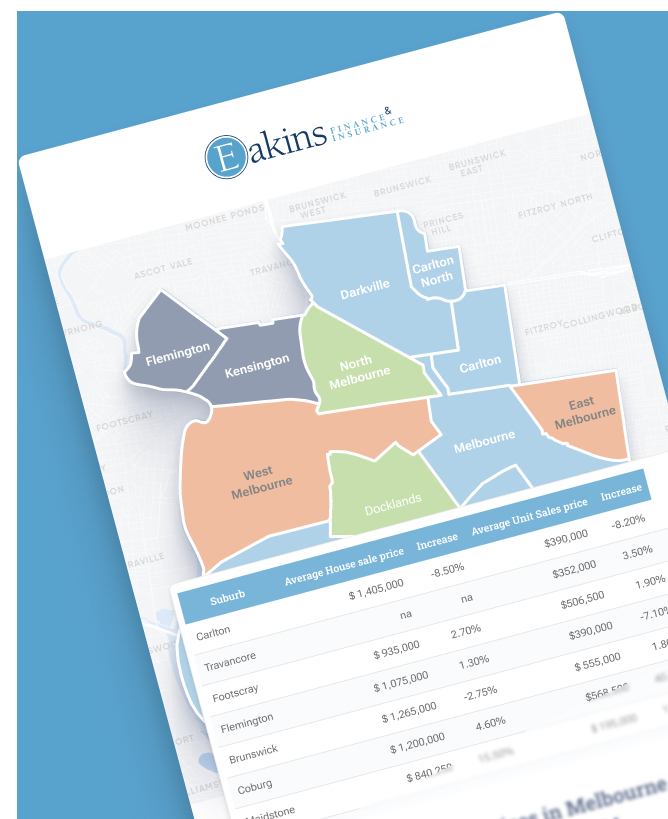
Find more affordable properties in Melbourne using the latest data. Download the full list today.


